Learn how to calculate profit and loss in the stock market using simple formulas and examples in rupees. Understand stock returns, average buying price, brokerage, STT, GST, CAGR, intraday trading, and Indian capital gains tax.
Official inflation figures show how prices change across a broad basket of goods and services, but your household may experience inflation differently. Learn how to calculate your personal inflation rate in India using your actual expenses, compare it with CPI, and understand what it means for your salary, savings, and investments.
November 2026 brings important financial deadlines and regulatory updates for Indian taxpayers, pensioners, businesses and savers. Learn about the pension life certificate deadline, GST changes, income tax filing extensions, FD interest rates and banking updates—and understand which changes may affect you.
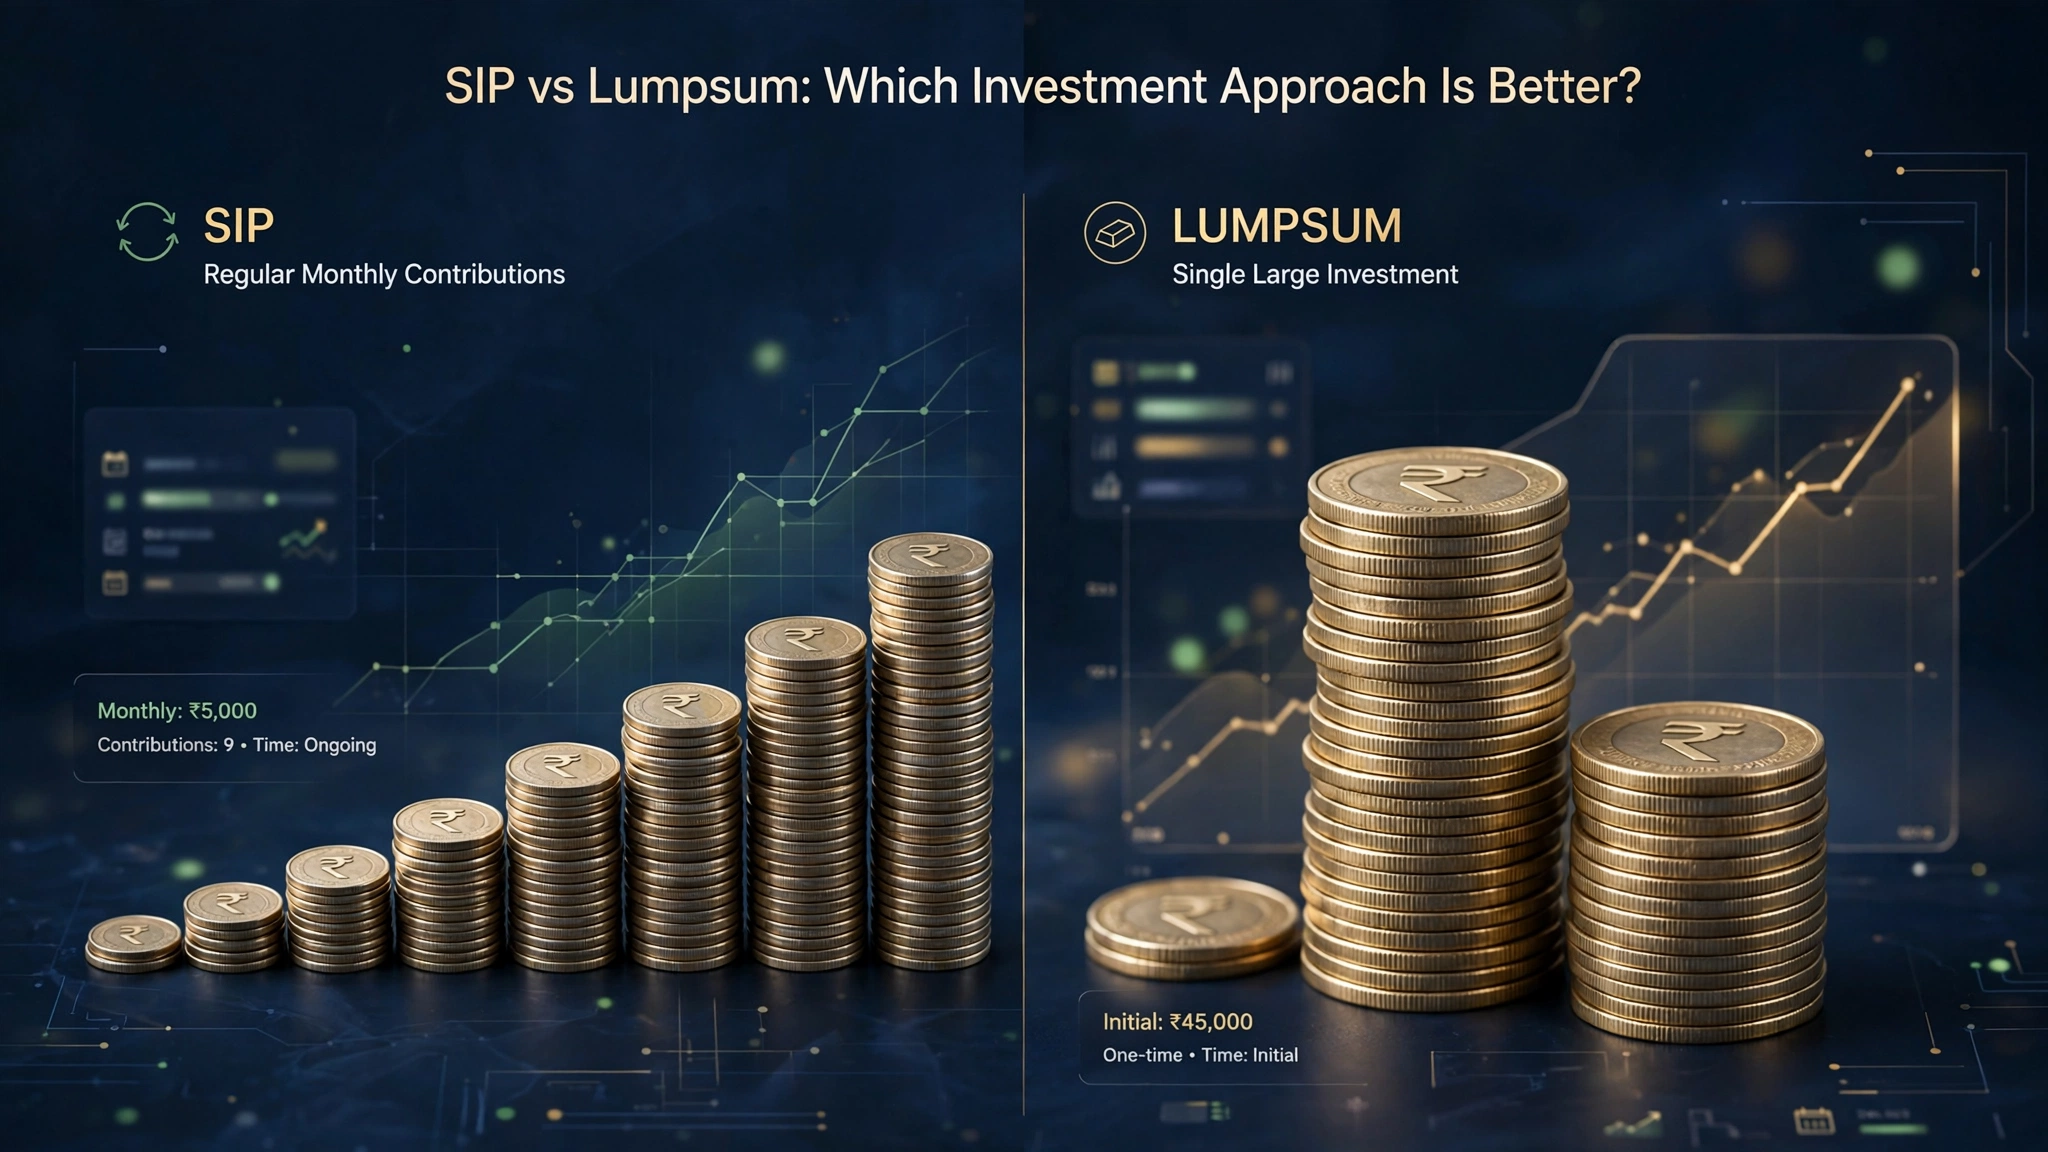
SIP and lumpsum investing are two ways to invest in mutual funds, but they suit different situations. Compare how they work, their risks, potential returns, rupee cost averaging, and when each approach may make sense for investors in India.
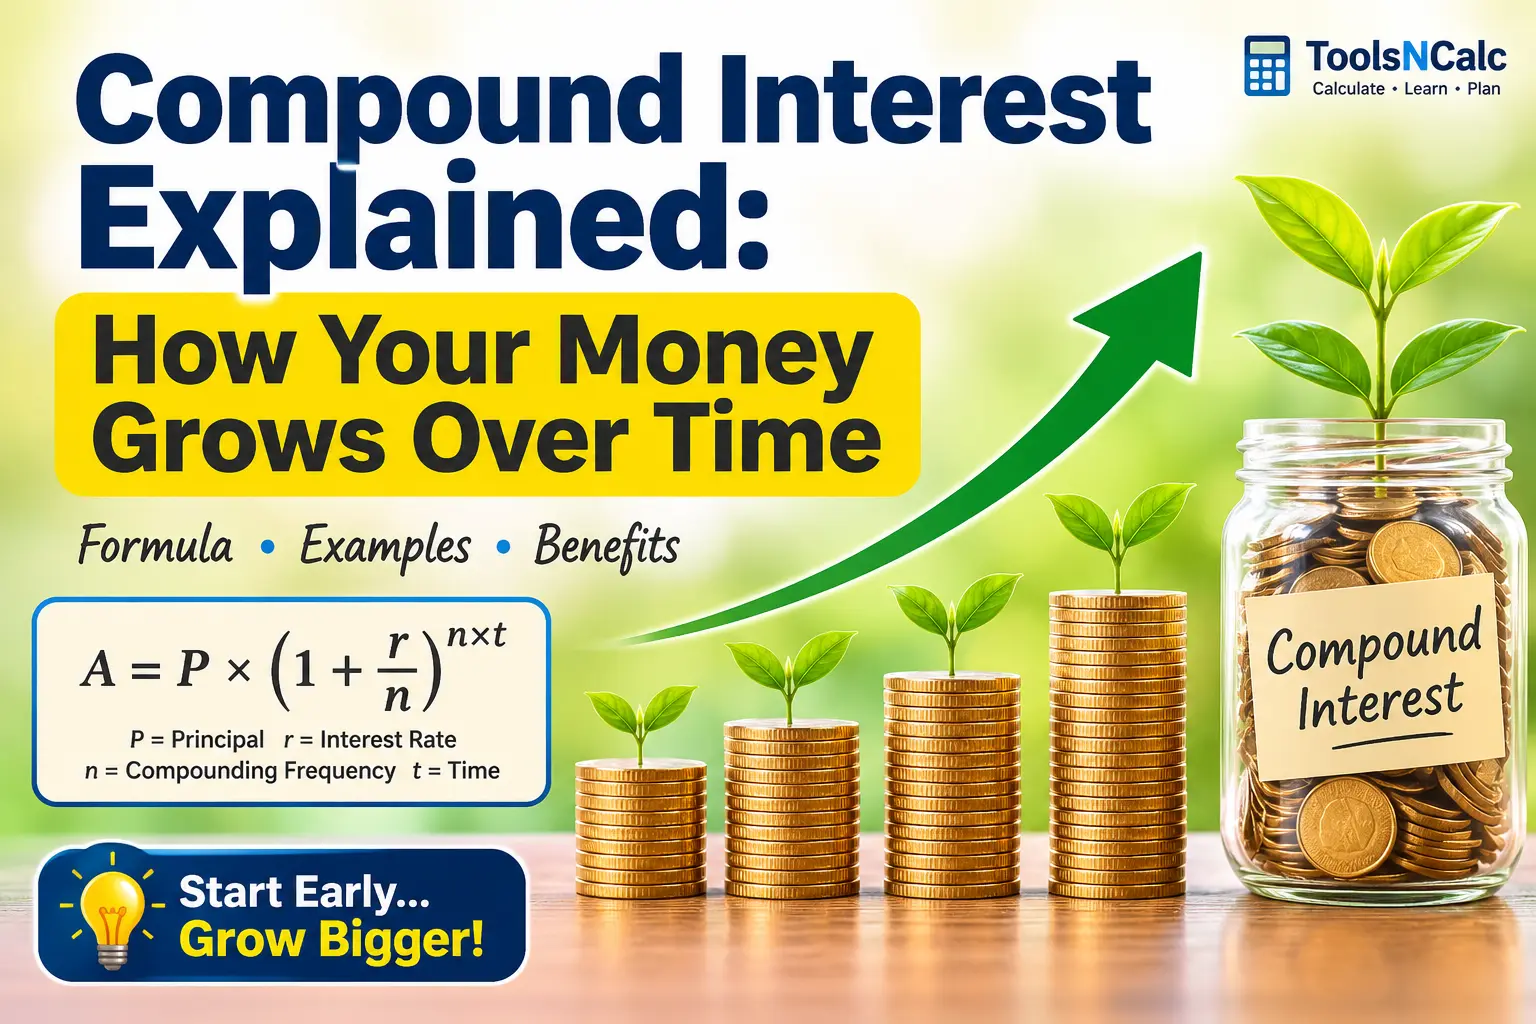
Discover how compound interest works and how it can help your money grow over time. Learn the compound interest formula, explore simple examples, understand the difference between compound and simple interest, and calculate potential savings growth using a compound interest calculator.
Guide to calculating potential stock returns using our investment tool: inputs like amount and rate, interpreting results for 2025. Beginner tips, scenarios, and charts to plan investments at toolsncalc.com.
Learn stocks for beginners in India: what stocks are, shares, dividends, risks, and how to buy. Simple explanations, real scenarios, and calculators to start investing in 2025 at toolsncalc.com.
Discover budgeting basics for beginners in India: step-by-step guide with 50/30/20 rule, tips, mistakes to avoid, and real examples to manage your money in 2025. Use toolsncalc.com calculators for effective financial planning.
Discover effective debt management strategies in India: snowball vs. avalanche methods, budgeting tips to pay off debt faster in 2025. Real scenarios, charts, and calculators for financial freedom at toolsncalc.com.
Discover credit cards in India: benefits like rewards, risks such as debt, and smart usage tips for beginners in 2025. Real scenarios and calculators to use credit wisely at toolsncalc.com.
India’s 2025 GST overhaul simplifies tax slabs to 5%, 18%, and 40%, effective September 22, 2025. Discover the extensive list of products and services that have become cheaper or costlier, impacting households, businesses, and the economy.
In 2025, India's GST undergoes a major revamp with slabs simplified to 5%, 18%, and 40%, making essentials cheaper from September 22. Explore rate changes, impacts, and tools in this guide.
Learn how to maximize savings with compound interest in India using the formula A = P(1 + r/n)^(nt). Discover early saving benefits, real examples, and a calculator guide for 2025 at toolsncalc.com.
Uncover interest rates in India: simple vs. compound explained, their impact on savings and loans, with tips for 2025. Use toolsncalc.com calculators to optimize your finances.
Discover the essentials of savings accounts in India for 2025, including types, interest rates, and tips to choose the best one for your needs. Learn how to grow your savings effectively with expert insights and tools from toolsncalc.com.
<p>Managing your money effectively starts with choosing the right bank account. Whether you’re a student saving pocket money, a professional managing daily expenses, or a business owner handling frequ
<p><b>London, July 7, 2025</b> – Hollywood’s newest power couple, Andrew Garfield and Monica Barbaro, made waves at Wimbledon’s seventh day on July 6, 2025, confirming their romance with a chic, coord
<p><b>Silverstone, UK – July 6, 2025</b> – Nico Hulkenberg achieved a historic milestone at the 2025 British Grand Prix, securing his first-ever Formula 1 podium after 239 race starts. The 37-year-old
<p>At ToolsnCalc.com, we take pride in providing accurate financial calculations. This article explains the mathematical formulas powering our most popular financial tools.</p>
<h3>Compound Interest
Credit Cards 101: Benefits, Risks, and Smart Usage
September 13, 2025 |
Personal Finance |
By ToolsnCalc Team
Credit cards have become a staple in Indian wallets, with over 100 million cards in circulation as of 2025, according to RBI data. Issued by banks like HDFC, SBI, and ICICI, they offer convenience but require careful use to avoid financial pitfalls. This beginner's guide introduces credit cards, highlighting benefits like rewards, risks such as high interest rates and debt, and smart usage tips. With real-life scenarios and tools from toolsncalc.com, you'll learn how to use credit cards responsibly to build credit and save money, not lose it.
What is a Credit Card and How Does It Work?
A credit card is a plastic or digital card issued by a bank that lets you borrow money up to a pre-approved limit to make purchases, pay bills, or withdraw cash. In India, cards are regulated by the RBI, and banks charge interest only if you don't pay the full balance by the due date (typically 45–50 days interest-free).
Here's how it works:
Application and Approval: Banks check your credit score (via CIBIL), income, and documents like PAN and Aadhaar to approve a limit (e.g., ₹50,000–₹10 lakh).
Usage: Swipe or tap for payments; the bank pays the merchant, and you repay the bank.
Billing Cycle: Monthly statements show transactions, due date, and minimum payment (usually 5% of outstanding).
Repayment: Pay in full to avoid interest (18%–48% p.a. in India); minimum payment leads to interest on the balance.
For more on banking basics, read our Banks Explained article.
Benefits of Credit Cards
Credit cards offer perks that can save money if used wisely.
Rewards and Cashback: Earn points, cashback (1%–5%), or miles on spends. For example, HDFC Regalia offers 4 points per ₹150 on dining.
Build Credit Score: Timely payments improve your CIBIL score (above 750 is good), helping future loans.
Convenience and Security: EMI options, contactless payments, and fraud protection (RBI mandates zero liability for reported losses).
Interest-Free Period: Up to 50 days grace on purchases, useful for cash flow.
Additional Perks: Airport lounges, fuel surcharge waivers, or insurance from cards like SBI Prime.
Real-Life Scenario: Amit, a software engineer in Bangalore, uses his ICICI Amazon Pay card for online shopping, earning 5% cashback on Amazon purchases—saving ₹5,000 annually without paying interest by clearing dues monthly.
Risks of Credit Cards
While beneficial, credit cards can lead to financial trouble if misused.
High Interest Rates: In India, rates range from 18%–48% p.a. (3%–4% monthly), compounding if not paid in full.
Debt Trap: Minimum payments (5%) leave the balance accruing interest, leading to debt spirals.
Fees and Charges: Annual fees (₹500–₹10,000, waivable), late payment fees (₹100–₹1,000), and over-limit charges.
Overspending: Easy access can lead to impulse buys beyond your means.
Real-Life Scenario: Priya, a teacher in Delhi, maxed her ₹1 lakh SBI card on shopping, paying only minimum dues. Interest ballooned her debt to ₹1.5 lakh in a year, hurting her credit score. She used toolsncalc.com’s debt calculator to plan repayment.
Smart Usage and Payment Tips
To enjoy benefits without risks:
Pay in Full Monthly: Avoid interest; set auto-debit for dues.
Track Spending: Use bank apps to monitor limits and rewards.
Choose the Right Card: Match to your lifestyle—e.g., fuel cards for commuters.
Avoid Cash Advances: High fees (2.5%–3.5%) and immediate interest.
Build Good Habits: Keep utilization below 30% for a healthy credit score.
Emergency Use Only: Treat as a tool, not free money.
Credit cards in India offer rewards and convenience but come with risks like high interest and debt. By understanding basics, using responsibly, and paying on time, you can build credit and save. Try toolsncalc.com’s credit card payoff calculator to stay debt-free. Smart usage turns credit cards into an asset, not a liability.


Comments
Please login to post a comment.