There is no universal winner in the SIP vs lumpsum debate. A Systematic Investment Plan (SIP) may suit people who invest from regular income and want to spread purchases over time. A lumpsum investment may suit someone who already has money available and understands the risks of investing it all at once. The result depends on the fund, market path, investment horizon, and investor’s ability to tolerate losses.
Both are methods of investing in mutual funds—not separate mutual fund categories. Choosing SIP or lumpsum does not make an unsuitable fund suitable, and neither method guarantees profit.
What Is SIP in a Mutual Fund?
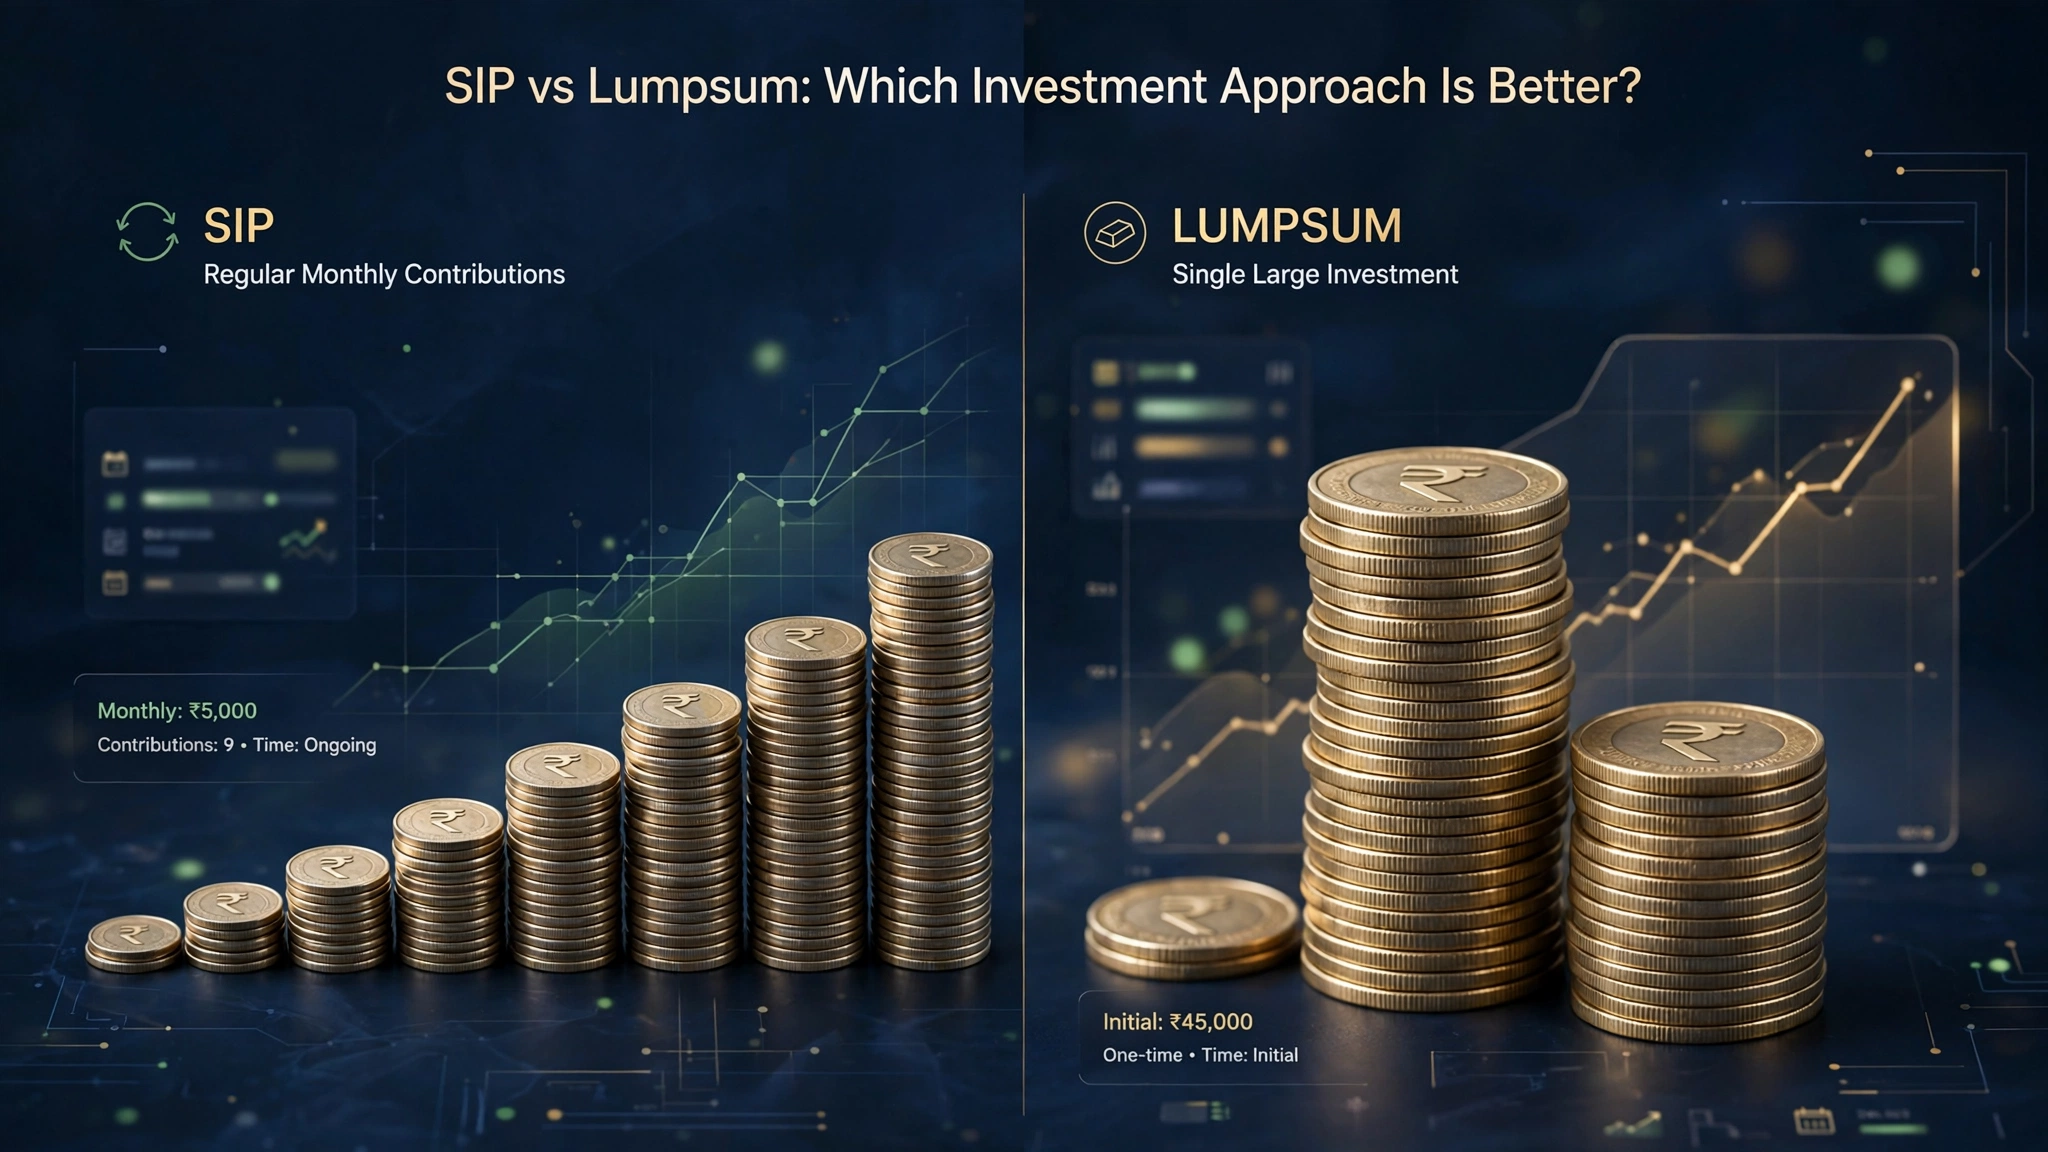
A Systematic Investment Plan (SIP) is a method of investing a fixed amount in a mutual fund at regular intervals, such as monthly or quarterly. For example, an investor might invest ₹5,000 every month instead of investing ₹60,000 at the beginning of the year.
Each instalment buys mutual fund units at the applicable Net Asset Value (NAV). Since the NAV changes, the same instalment may buy more units when the NAV is lower and fewer units when it is higher.
SIP is a way to automate regular investing. It is not a separate fund and does not itself determine the fund’s risk or returns. AMFI explains SIP and rupee cost averaging.
How does SIP work?
- Choose a mutual fund scheme after evaluating its objective, risk level, costs, and suitability.
- Decide the amount and investment frequency.
- Register the SIP and payment mandate through the fund house or a suitable platform.
- Instalments are invested according to the schedule and applicable terms.
- Review the investment periodically against your goals—not every time the market moves.
What Is a Lumpsum Investment?
A lumpsum investment means investing a single amount in one transaction. For example, someone with ₹1,00,000 available may invest the entire amount in a mutual fund on one date.
The full amount gets exposure to the market from the investment date. If the market rises afterward, the investor benefits from that exposure. If it falls, the entire invested amount experiences the decline from that point.
Lumpsum investing may be relevant when money is already available, such as a planned investment allocation from savings. It is not automatically the best choice just because the investor has a large amount.
SIP vs Lumpsum: Key Differences
| Feature |
SIP |
Lumpsum |
| Investment pattern |
Regular instalments |
One-time investment |
| Source of money |
Often salary or regular income |
Existing available capital |
| Market entry |
Spread across dates |
Concentrated on one date |
| Timing risk |
Reduces dependence on one entry date |
More exposed to market level on entry date |
| Rupee cost averaging |
Occurs naturally across instalments |
Not achieved through a single purchase |
| Cash-flow discipline |
Encourages regular investing |
Requires decision about available amount |
| In a steadily rising market |
Later money may enter at higher prices |
Full amount participates from the start |
| In a falling market |
Later instalments may buy at lower NAVs |
Entire amount is exposed after entry |
| Return guarantee |
No |
No |
Important: SIP does not remove market risk. It spreads the timing of purchases. The mutual fund’s underlying assets can still fall in value.
SIP vs Lumpsum Returns Comparison
Returns depend on the market path and when each investment is made. Consider a simplified illustration:
- SIP: ₹10,000 invested at the end of each month for 12 months.
- Lumpsum: ₹1,20,000 invested at the beginning of the period.
These approaches do not have the same timing of exposure. The lumpsum is invested immediately; the SIP amount enters gradually. Therefore, a comparison must account for when each rupee is invested.
In a steadily rising market, the lumpsum may benefit because more money is invested earlier. In a falling or volatile market, SIP instalments may purchase units at lower NAVs later in the period. Neither outcome is guaranteed.
Hypothetical SIP calculator illustration
Suppose an investor contributes ₹10,000 per month for 10 years. Total contributions are:
₹10,000 × 12 × 10 = ₹12,00,000
A calculator may estimate a future value using an assumed annual return, such as 10%. This is a mathematical illustration only. Mutual fund returns are market-linked, fluctuate, and are not earned at a fixed monthly rate.
Do not treat a calculator’s assumed rate as a forecast or promise. Actual outcomes depend on market performance, expenses, taxes, and timing.
Rupee Cost Averaging Explained
Rupee cost averaging means investing a fixed amount regularly, so the investor buys more units when the NAV is lower and fewer units when it is higher.
Example: An SIP of ₹1,000 buys:
| NAV |
Units purchased with ₹1,000 |
| ₹20 |
50 |
| ₹10 |
100 |
| ₹25 |
40 |
The same amount buys different numbers of units because the NAV varies.
This can help average the purchase cost across different market levels. However, rupee cost averaging does not guarantee profit, prevent losses, or ensure that the average purchase price is below the final market price. In a prolonged decline, the investment may still lose value. AMFI’s SIP explanation describes these limitations.
Rupee cost averaging vs market timing
Market timing means trying to choose the best time to invest or exit. This is difficult because future market movements are uncertain.
SIP can reduce the need to decide on one entry date, but it does not eliminate the need to select an appropriate fund, asset allocation, or investment horizon.
Is SIP Safe for Beginners? Is SIP Safer Than Lumpsum?
SIP may be easier for some beginners to manage because it uses regular contributions and reduces the pressure to invest a large amount on one date. But SIP is not inherently safe.
The risk depends primarily on the mutual fund’s holdings and investment objective. An SIP in an equity fund can experience substantial losses during market declines. A lumpsum investment in a lower-risk asset may have a different risk profile.
SEBI and AMFI explain that mutual fund investments are subject to market risks, and returns are not guaranteed. Check the scheme’s Riskometer, investment objective, and documents. SEBI investor education | AMFI risk information.
Which Is Better: SIP or Lumpsum?
The better approach depends on your financial situation—not a general rule.
SIP may suit you if:
- You receive regular income and invest from each salary.
- You prefer to spread purchases over time.
- You are building an investing habit.
- You do not have a large amount available today.
- You want to avoid making a single market-entry decision.
Lumpsum may suit you if:
- You already have money earmarked for investment.
- You have an appropriate emergency fund and no immediate need for the money.
- You understand that the investment may fall soon after purchase.
- Your investment plan and risk tolerance support investing the full amount now.
What if you have a large amount but are nervous about investing it?
You could compare investing immediately with a planned staggered approach. Some investors use a Systematic Transfer Plan (STP), where money is transferred from one mutual fund scheme to another at regular intervals, subject to availability and suitability. This does not guarantee better returns and can involve market, liquidity, and tax considerations.
Avoid choosing a strategy solely because you expect a market crash or rally. Forecasting market timing consistently is difficult.
SIP vs Fixed Deposit (FD)
SIP and fixed deposits are not equivalent products.
| Feature |
SIP in a mutual fund |
Fixed Deposit |
| Product |
Investment method for mutual funds |
Bank deposit product |
| Returns |
Market-linked; not guaranteed |
Rate generally specified for deposit tenure, subject to terms |
| Capital risk |
Depends on fund; market value can fall |
Different risk profile; bank and deposit terms matter |
| Liquidity |
Depends on scheme, exit load, settlement, and restrictions |
Depends on deposit terms and premature withdrawal rules |
| Typical use |
Goals where market risk is acceptable |
Savings/deposit goals where deposit terms and rate certainty matter |
Do not compare a projected SIP return with an FD rate as if both were guaranteed. Compare risk, liquidity, time horizon, taxes, and product terms.
How to Start a SIP Online in India
The exact process varies by fund house and platform, but commonly includes:
- Complete the required KYC process.
- Choose a mutual fund scheme based on your goals, risk tolerance, and time horizon.
- Review the scheme information, Riskometer, costs, and documents.
- Select SIP amount, frequency, and date.
- Set up the payment mandate.
- Confirm the details and keep transaction records.
Use regulated and legitimate channels. Avoid selecting a mutual fund solely because it is trending or has recently delivered high returns. Past performance does not guarantee future performance.
What Is the Minimum Amount for SIP Investment?
There is no single minimum SIP amount that applies to every mutual fund. The minimum depends on the scheme and fund house. Some schemes may allow SIPs starting at ₹500 or less, while others may require more.
Check the latest scheme details before registering. Do not assume a minimum advertised for one fund applies to all funds. AMFI SIP information.
Can I Pause or Stop My SIP?
SIP pause, cancellation, and modification options depend on the mutual fund and the platform through which it was registered.
- Check whether your AMC or platform offers a pause facility.
- Review notice periods and permitted pause duration.
- You may be able to cancel future instalments without redeeming existing units.
- Cancelling an SIP does not automatically sell or redeem units already purchased.
- Redemption is a separate transaction and may involve exit loads, settlement periods, taxes, or scheme-specific restrictions.
Check the current terms before taking action.
When to Invest Lumpsum in Mutual Funds
There is no universally correct market level or date for a lumpsum investment.
Before investing, consider:
- Whether the money is truly available for investment.
- Whether you have an emergency reserve.
- Your investment horizon.
- The fund’s risk level and asset allocation.
- Whether a market decline would cause you to sell in panic.
- Whether the investment fits your broader financial plan.
Lumpsum investment during a market crash
A market decline may make asset prices lower than earlier levels, but it does not prove that the market has reached its bottom. Prices may fall further.
Investing during a crash requires risk capacity, a suitable time horizon, and a plan. Do not invest emergency money or funds needed soon simply because prices have fallen.
How to Use a ToolsNCalc SIP or Lumpsum Calculator
A calculator can help compare hypothetical scenarios—but it cannot predict actual mutual fund returns.
SIP calculator
- Enter the monthly SIP amount.
- Enter the investment duration.
- Enter an assumed annual return.
- Calculate the estimated future value.
- Change assumptions to compare scenarios.
Lumpsum calculator
- Enter the initial investment.
- Enter the duration.
- Enter an assumed annual return.
- Calculate the estimated future value.
- Compare different assumptions.
Label the output as an estimate. Actual mutual fund returns are variable and may be lower or negative.
ToolsNCalc SIP Calculator
ToolsNCalc Lumpsum Calculator
Replace these with the exact calculator URLs when available.
Frequently Asked Questions
1. Which is better, SIP or lumpsum?
Neither is always better. SIP can suit regular income and staggered investing. Lumpsum can suit money already available. Returns depend on market path, timing, fund, and investor circumstances.
2. Is SIP safer than lumpsum?
SIP spreads investment entry across dates, which can reduce the risk of investing the entire amount at one market level. It does not eliminate market risk or guarantee lower losses.
3. What is the minimum amount for SIP investment?
The minimum depends on the mutual fund scheme and AMC. Some allow small instalments, but there is no universal minimum for every scheme. Verify current scheme terms.
4. Can I pause my SIP?
Some mutual funds or platforms offer a pause facility, but rules vary. Check the AMC or platform terms. Cancellation of future instalments may also be available.
5. Does SIP guarantee returns?
No. SIP is an investment method, not a guaranteed-return product. Returns depend on the underlying mutual fund and market performance.
6. Can I invest lumpsum during a market crash?
You can if the investment fits your financial plan and risk tolerance, but a market decline can continue. A crash does not guarantee prices have reached their bottom.
Final Thoughts
SIP and lumpsum investing are two ways to invest—not competing products with a guaranteed winner.
SIP may help investors contribute regularly and spread their entry dates. Lumpsum investing gives immediate market exposure to money already available. Choose based on cash flow, investment horizon, risk tolerance, and goals.
Understand the mutual fund before choosing the investment method. Check the scheme’s risk level and official documents, and do not assume SIP protects you from losses.
Disclaimer: This article is for educational purposes only and is not investment, financial, or tax advice. Mutual fund investments are subject to market risks. Returns are not guaranteed. Read scheme-related documents carefully and consider professional advice if needed.
Internal link suggestions
- SIP Calculator — anchor: “SIP Calculator”
- Lumpsum Calculator — anchor: “Lumpsum Calculator”
- Compound Interest Calculator — anchor: “compound interest calculator”
- Inflation Calculator — anchor: “inflation calculator”
- “Compound Interest Explained” — anchor: “how compounding works”
- “Mutual Funds for Beginners” — anchor: “mutual fund basics”
External source suggestions


Comments
Please login to post a comment.